Fossil Returns to Profit and Sales Growth, Raises 2026 Outlook
The watchmaker posted its first quarterly sales gain since early 2022 and a swing to profit, as CEO Franco Fogliato says its turnaround is ahead of plan.
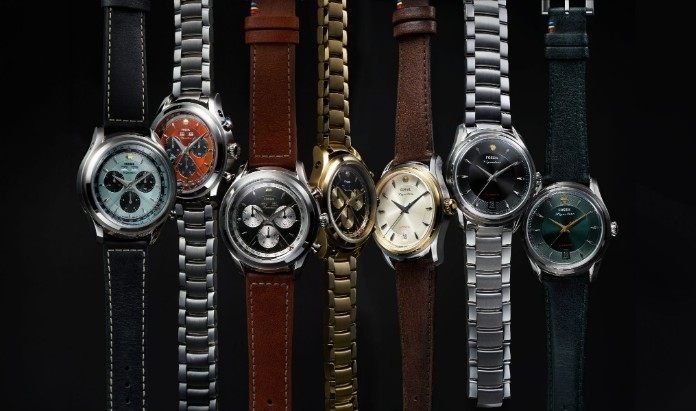
Fossil Group, the Texas-based watch and accessories maker that has spent years shrinking under pressure from smartwatches and fading mall traffic, said Tuesday that it swung to a profit and grew sales for the first time in more than four years in its third quarter, and it raised its full-year outlook. Chief Executive Franco Fogliato told CNBC the company’s turnaround is running roughly a year and a half ahead of the timeline it originally set.
What happened
For the quarter ended Oct. 3, Fossil reported net sales of $271.2 million, up 0.4% from $270.2 million a year earlier, according to the company’s earnings release filed with the U.S. Securities and Exchange Commission. Excluding currency swings, sales rose 2%. CNBC noted it was the first year-over-year sales increase since the first quarter of fiscal 2022.
The modest top-line gain came with a much larger shift in profitability. Fossil posted operating income of $25.3 million, or 9.3% of sales, compared with an operating loss of $21.7 million a year earlier. Net income was $11.7 million, or 19 cents per share, versus a net loss of $39.9 million, or 76 cents per share, in the same quarter of 2025. CNBC reported that it was Fossil’s first quarterly net profit since the third quarter of 2022.
The results came in well above Wall Street’s expectations. A preview published Nov. 3 by Earnings Whispers, a financial data site, said analysts had forecast revenue of about $247.2 million and earnings of roughly 3 cents per share.
Key figures from the release include:
- Gross margin of 59.8%, up 10.8 percentage points from 49% a year earlier.
- Operating expenses down 11.1% to $137 million, according to CNBC.
- Traditional watch sales up 6.4% in constant currency, while leather goods fell 20.5% and jewelry fell 10.8%.
- Smartwatch sales of just $0.9 million, down from $3.8 million.
Why it matters
Fossil was a fixture of department-store watch counters in the 2010s, when its sales and share price peaked. Since then, CNBC noted, the company has struggled with the rise of smartwatches, a heavy debt load and declining foot traffic at malls, and its stock has lost the vast majority of its value. The quarter offers the clearest sign yet that the strategy under Fogliato, who joined the company in 2024, is gaining traction.
Fogliato told CNBC that making the company smaller was the single biggest factor in shoring up its balance sheet, with the goal of reaching a stable base before trying to grow again. That has meant closing stores, moving away from heavy discounting toward full-price selling, improving marketing and broadening its product range. Fossil has also stopped chasing the smartwatch market and is investing again in traditional analog watches, which CNBC said now make up about 86% of sales.
“Fossil is literally having a comeback,” Fogliato told the network. In the earnings release, he said the company’s three strategic pillars were “translating to top line growth and accelerating profitability.”
Where growth is coming from
The gains were uneven. Sales in Asia rose 15.1% in constant currency, helped largely by India, according to CNBC, while the Americas were essentially flat and Europe fell 5.6%. Wholesale sales increased 4.4%, but direct-to-consumer sales dropped 5.9%, which the company attributed to its aggressive downsizing of its own retail footprint. Fossil ended the quarter with 174 stores, down from 204 a year earlier, after closing 23 locations, opening four and converting 11 to franchise operations.
Fogliato said growing the home market remains the top priority, with international markets, especially Asia, a secondary driver.
What comes next
Fossil now expects full-year 2026 net sales of $980 million to $990 million, excluding currency effects, and an adjusted operating margin of 5.5% to 6.5%. It also expects positive free cash flow for the year. Earnings Whispers reported that the previous sales outlook was roughly $954 million to $974 million; CNBC described the earlier forecast as a 3% to 5% decline from the prior year’s sales of just over $1 billion.
Risks remain. The company carried $208 million in total debt at the end of the quarter against total liquidity of $111.7 million, and inventories rose 13.4% from a year earlier, according to the release. Management had previously pointed to a return to companywide sales growth in the fourth quarter, a milestone the company has now reached a quarter early.